Explore how U.S. investment banks drive mergers, capital raising and corporate finance, offering insights into Wall Street and America's next business cycle.
Explore how U.S. investment banks drive mergers, capital raising and corporate finance, offering insights into Wall Street and America's next business cycle.
Image courtesy of Yelp
America's biggest banks are preparing to reveal more than quarterly profits. As borrowing costs, energy prices and economic uncertainty reshape business decisions, lending demand, credit quality and corporate financing activity could offer important clues about the next phase of the U.S. economy.
The Economy's Most Important Signals May Be Inside the Banks. Every business cycle leaves clues before its direction becomes obvious. Companies begin delaying investments, households become more cautious, lenders reconsider their risks and borrowers adjust their expectations. By the time these changes appear clearly in employment figures or economic growth statistics, businesses may already have changed course.
America's banks occupy a unique position in this process. They lend to companies expanding their operations, finance households buying homes and cars, provide credit to property developers and help businesses manage their cash flow. Their balance sheets offer a view of economic activity that extends far beyond Wall Street.
As major U.S. banks prepare to report third-quarter 2026 earnings, investors are paying close attention to lending growth, deposit costs, investment banking activity and the quality of outstanding loans. Reuters reported on October 8 that investors were assessing how higher Treasury yields could affect financing costs and dealmaking, even as expectations for major banks' earnings remained relatively strong.
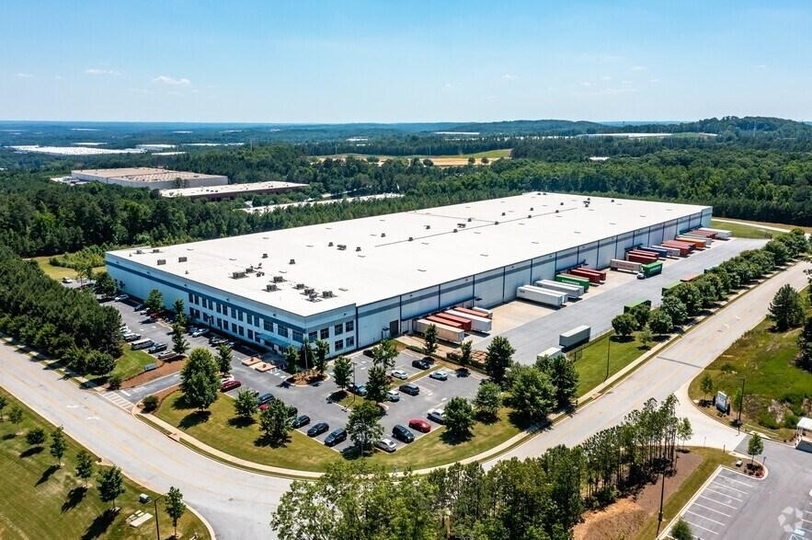
When businesses expect stronger demand, they often borrow to purchase equipment, expand facilities, increase inventories or acquire competitors. When confidence weakens, companies may postpone investments, preserve cash and reduce their reliance on external financing. Commercial and industrial lending therefore provides one useful window into corporate decision-making.
The Federal Reserve's July 2026 Senior Loan Officer Opinion Survey reported that banks had generally left commercial and industrial lending standards unchanged during the second quarter. Demand for business loans from large and middle-market companies strengthened, while demand from smaller businesses remained broadly unchanged. This suggests a nuanced picture rather than a straightforward economic boom or contraction.
Larger companies may have the confidence, balance sheets and access to capital needed to pursue new investments. Smaller businesses, however, may remain more cautious about borrowing, particularly when operating expenses and financing costs make expansion harder to justify. For investors, the distinction matters. An increase in lending to large companies does not necessarily mean that economic growth is spreading evenly across the economy.
The next question is what businesses are borrowing for. Loans used to finance productive investment can support future revenue and employment. Borrowing used primarily to cover operating shortfalls may indicate that companies are under pressure.
What to watch: Commercial loan growth, demand for revolving credit lines, business investment plans and commentary from bank executives about small-business customers.
Commercial and industrial (C&I) lending is money that U.S. banks lend to businesses to help them operate, purchase equipment, manage cash flow, expand production, or finance day-to-day activities. In simple terms, it is business loans provided by banks to companies, rather than loans made to individuals to buy homes or cars.
How C&I lending works. Imagine an American plywood importer that purchases hardwood plywood from Indonesia and sells it to U.S. furniture manufacturers.
Step 1 — The company requests a loan
The importer needs $500,000 to purchase plywood, pay shipping costs and cover expenses before customers pay their invoices.
Step 2 — The bank provides financing
The bank approves a $500,000 business credit facility, subject to the company's creditworthiness, financial position and loan terms.
Step 3 — The company conducts business
The importer purchases inventory, receives the shipment and sells the plywood to customers.
Step 4 — The company repays the bank
Once customers pay their invoices, the importer repays the loan and interest according to the agreed terms. This is a simplified example of C&I lending. The actual facility might be structured as a revolving credit line, a term loan or another type of commercial financing.
Types of businesses use C&I loans. Manufacturing: Buy machinery, raw materials and production equipment. Import and export: Finance inventory, shipping and customer payment cycles. Retail: Purchase merchandise and fund seasonal inventory. Transportation: Finance fleet operations and working capital. Technology: Fund operating expenses and business expansion. Agriculture: Purchase supplies and finance operating costs. Wholesale distribution buy goods before receiving payment from customers. Important distinction: C&I loans generally finance business operations and commercial activities. A loan specifically secured by a factory, office building or other real estate may instead be classified as commercial real estate lending, depending on its structure and purpose.
C&I lending is useful because it helps show whether American businesses are borrowing to operate and grow.
When business lending increases. Companies may be expanding production, building inventory, hiring employees or investing in new opportunities. However, increased borrowing can also reflect higher costs or financial stress, so the reason for the borrowing matters.
When business lending stagnates. Companies may be postponing investments, relying on existing cash reserves or seeing less demand for their products.
When business lending contracts. Businesses may be reducing expansion plans, banks may be tightening lending standards, or borrowers may be paying down debt. A sustained decline can be a warning sign, but it does not automatically mean a recession is coming.
Commercial and industrial lending offers a window into the decisions being made across corporate America. When companies borrow to purchase machinery, finance inventory or expand production, they can help drive economic growth. But when borrowing weakens, banks tighten credit standards or repayment problems increase, the same lending data can reveal mounting pressure on businesses. The key is not simply whether commercial loans are rising or falling, but why those changes are happening.
The central lesson is that C&I lending measures an important part of the relationship between banks and the businesses that power the U.S. economy. It is a valuable economic signal, especially when analyzed alongside employment, consumer spending, interest rates and corporate earnings.
The cost of money influences nearly every major business decision, from buying a home to financing a factory. When interest rates remain elevated, companies must evaluate whether expected returns justify higher borrowing costs. Property developers may delay projects, businesses may reconsider acquisitions, and households may postpone purchases that require financing.
Banks face a challenge of their own. They must balance the interest earned on loans against the cost of attracting deposits and maintaining sufficient funding. Higher rates can improve earnings on some loans, particularly when lending rates adjust faster than deposit costs. But the benefit is not automatic. Competition for deposits, customer refinancing, credit losses and the changing value of existing investments can all affect profitability.
The recent environment makes this balance especially important. Reuters' October 8 reporting identified higher Treasury yields as a key issue for investors evaluating major U.S. banks, including the implications for dealmaking, lending and funding costs.
For businesses, the practical consequence is that access to capital matters just as much as the headline interest rate. A company may have an attractive expansion plan but still decide against proceeding if the cost of financing makes the expected return insufficient.
For investors, bank earnings calls can reveal how lenders are adapting their pricing, managing deposits and evaluating new loan applications.
What to watch: Net interest margins, deposit costs, loan pricing and management guidance on the sustainability of lending profitability.
As of October 11, 2026, U.S. borrowing costs are relatively high for many consumers and businesses. One important distinction: major banks such as JPMorgan Chase, Bank of America, Wells Fargo and Citibank do not have one universal interest rate. They offer different rates depending on the loan, the borrower and the terms.
The Federal Reserve's effective federal funds rate was 3.88% in the latest available data for October 8, while the widely quoted U.S. bank prime rate was 7.00%.
Current U.S. interest-rate snapshot. Latest available figures as of October 8–9, 2026; these are market benchmarks, not a guaranteed offer from any individual bank.
Federal funds effective rate: 3.88%
Interbank overnight benchmark. Bank prime rate: 7.00%
Reference for many variable-rate loans. 30-year fixed mortgage: 7.49%
How do the major U.S. banks compare?
The following are major U.S. banks and the way their business loan rates are structured. Their actual loan pricing is generally customized, so it would be misleading to assign each bank one fixed commercial lending rate.
JPMorgan Chase. Business loans and revolving credit facilities are priced according to the facility, borrower creditworthiness and applicable benchmark. Investors are watching lending growth and funding costs in its October earnings report.
Bank of America. Offers business credit lines and term loans. Its published terms show that some credit facilities use the prime rate, with actual pricing affected by creditworthiness and customer relationships.
Wells Fargo. Business financing rates depend on the loan product and borrower profile. Its commercial loan growth is one of the indicators investors are monitoring during the current earnings season.
Citigroup. Provides corporate and commercial financing, with pricing determined by the borrowing arrangement, credit risk and relevant market benchmarks. Its third-quarter results are scheduled for October 13.
The American consumer remains central to the business outlook because household spending supports a broad range of industries, including retail, travel, restaurants, automobiles and housing. Banks can provide insight into household financial conditions through credit-card balances, auto loans, mortgage lending and repayment performance.
The Federal Reserve's July survey reported tighter standards for credit-card lending and weaker demand for auto loans. Banks also described consumer lending standards as being toward the tighter end of their historical ranges. These findings do not establish that a consumer recession is imminent. They do, however, highlight an important distinction: the ability and willingness of households to borrow can change even while spending elsewhere in the economy remains resilient.
A household facing higher housing, insurance, food or transportation costs may cut discretionary purchases before missing a loan payment. A consumer who can no longer qualify for affordable credit may delay replacing a vehicle or reduce spending on other goods and services.
For retailers and consumer-facing businesses, these changes can influence sales volumes, product mix and pricing strategies. Banks' credit-card delinquency rates, charge-offs and auto-loan performance can help determine whether financial pressure is becoming more widespread. Those figures must be considered alongside employment, wages, savings and household debt levels rather than interpreted in isolation.
What to watch: Credit-card delinquencies, auto-loan losses, consumer loan growth and management commentary about lower-income borrowers and household spending.
Consumer credit is one of the most useful indicators for understanding the U.S. business outlook because it shows how American households are borrowing, repaying debt and financing their spending. It needs to be read alongside employment, wages, savings, inflation and household spending. But several types of credit can provide early warning signals about the direction of the economy.
Credit cards - High-frequency signal. Credit cards finance everyday purchases, including groceries, fuel, restaurants and online shopping. If balances and missed payments rise together, households may be relying more heavily on borrowing to maintain spending. Business impact: Retail sales, restaurants, travel, e-commerce and luxury goods.
Auto loans - Auto loans help finance vehicle purchases. Weak demand can affect car manufacturers, dealerships, auto-parts suppliers and lenders. Rising delinquencies may indicate that monthly payments are becoming difficult for some borrowers. Business impact: Automotive sales, manufacturing, insurance and vehicle servicing.
Student loans. Student debt repayments can influence the disposable income available to younger households. Higher repayment burdens may affect spending on housing, restaurants, transportation and discretionary goods. Business impact: Consumer spending, rental housing and businesses targeting younger customers.
Personal loans. These can finance household purchases, debt consolidation and unexpected expenses. Rapid growth may reflect access to financing, but it can also indicate that some consumers are struggling to meet expenses. Business impact: Household purchasing power, consumer finance companies and retailers.
Home-equity credit lines. Homeowners can borrow against accumulated property equity. These loans may support renovations and spending, but falling property values or higher variable rates can increase financial risk. Business impact: Home improvement retailers, contractors and residential property markets. Note: Home-equity loans and mortgages are secured by real estate, so they are excluded from the Federal Reserve's standard consumer-credit totals.
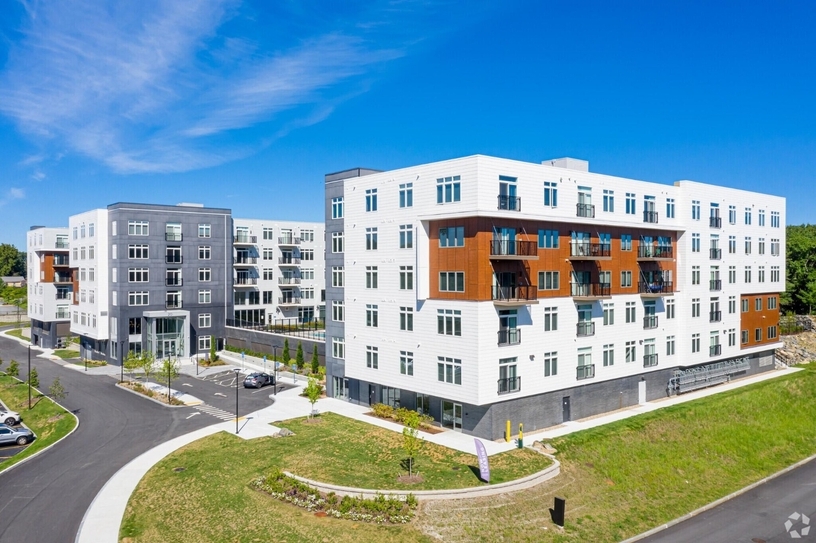
Commercial real estate offers another important measure of the next business cycle. Office buildings, apartment complexes, retail properties and industrial facilities depend on different combinations of rental income, occupancy, financing and property values. When interest rates rise or tenants reduce their space, property owners can face higher financing costs and weaker cash flow at the same time.
Banks with significant commercial real estate exposure must assess whether borrowers can refinance maturing loans on acceptable terms. The Federal Reserve's July survey reported that banks generally eased standards for commercial real estate lending during the second quarter, while demand was broadly unchanged. The survey also indicated that standards for some property categories remained relatively restrictive compared with historical experience.
This combination matters. Easing lending standards may signal that lenders are becoming more comfortable with selected borrowers or competing more actively for business. It does not necessarily mean that every property segment has recovered.
A well-leased industrial property in a supply-constrained location can have a very different financial outlook from an older office building with declining occupancy and a large loan approaching maturity.
Investors should therefore look beyond broad claims about a real estate recovery. The quality of the property, the borrower's equity, rental income and refinancing terms are often more important than the sector label. For banks, commercial property loans are also a test of underwriting discipline. Expanding credit too aggressively during a recovery can create problems later if property valuations or rental income disappoint.
What to watch: Commercial real estate loan delinquencies, loan-loss provisions, refinancing activity, office exposure and differences between property sectors.
U.S. commercial real estate in October 2026
The market is recovering in some sectors, but higher interest rates are creating a new test for property investors. The latest National Association of Realtors report, published in October, describes improving office fundamentals, stronger apartment demand and resilient retail conditions, while industrial property is gradually absorbing excess supply.
The key point is that the U.S. commercial property market is no longer one uniform story. Location, building quality, tenant demand and financing terms increasingly determine whether an investment performs well.
Which commercial property sectors are performing better?
Office buildings. Office demand is improving, particularly for high-quality buildings in major business districts. Prime offices are attracting tenants, while older buildings with outdated facilities continue to face challenges. Business opportunity: Prime offices, renovation and repositioning of well-located properties. Main risk: High vacancy, expensive renovations and refinancing difficulties for older buildings.
Multifamily apartments. Apartment demand is strengthening as new construction slows and the market absorbs excess supply. However, rent growth remains limited in some markets, and higher financing costs continue to pressure certain owners. Business opportunity: Apartments in locations with durable employment and manageable new supply. Main risk: Debt maturities, operating expenses and competition from recently completed developments.
Industrial and logistics property. Demand is improving, but the sector is still adjusting to the supply built during earlier expansion. Logistics properties account for much of the leasing activity, while rent growth remains restrained. Business opportunity: Strategically located distribution facilities and modern industrial buildings. Main risk: Local oversupply, tenant concentration and weaker demand for less competitive facilities.
Retail property. Retail availability remains relatively low, and leasing demand is broadening across several formats. Neighborhood and power centers have benefited from limited available space, although new supply could create pressure in some locations. Business opportunity: Well-located, grocery-anchored neighborhood centers. Main risk: Tenant failures, changing shopping behavior and local competition.
Hotels and hospitality. Hotel room rates and revenue per available room remain above 2019 benchmarks, but occupancy has been constrained in some business-travel markets. High borrowing costs are also limiting investment activity. Business opportunity: Properties supported by strong tourism or diversified travel demand. Main risk: Operating costs, seasonal demand and sensitivity to an economic slowdown.
The biggest concern is commercial property financing
The most important risk to understand right now is not simply whether buildings are occupied. It is whether property owners can refinance their loans when they mature. A refinancing rate of 8% instead of 5% would increase annual interest expense by $300,000 if the entire $10 million remained outstanding. This illustration excludes principal repayment, fees and other loan terms.
If rental income has not increased enough to cover the additional interest, the owner may need to inject more equity, negotiate new terms, sell the property or default.
This is a real concern in the current market. Trepp reported that 11.42% of commercial mortgage-backed securities loans were in special servicing in August 2026, the highest level since February 2013, according to the October 6 Wall Street Journal report. Special servicing indicates loans requiring additional attention because of problems such as missed payments or refinancing difficulties; it does not mean every such loan has defaulted. However, the picture is not uniformly deteriorating. The Mortgage Bankers Association reported on September 28 that commercial mortgage delinquencies were mixed in the second quarter, with some categories improving and others worsening.
Where might the investment opportunities be?
For investors, the market increasingly rewards careful property selection rather than simply buying commercial real estate at a discount. One important point: a discounted building is not automatically a good investment. A low purchase price can be offset by expensive debt, major capital expenditure, weak tenants or years of poor cash flow.
CBRE's August 2026 midyear outlook projected U.S. commercial real estate investment volume to increase by approximately 16% year over year to $605 billion in 2026. That forecast reflected continued investment activity, but it preceded the latest October interest-rate shock and should be reassessed against current financing conditions.
Banks do more than provide traditional loans. Their investment banking divisions advise on mergers and acquisitions, help companies issue debt and equity, and support capital-market transactions. These activities can provide another perspective on corporate confidence.
When business leaders feel comfortable with the outlook, they may be more willing to acquire competitors, raise capital, sell assets or pursue public listings. When uncertainty increases, transactions can be postponed while companies wait for clearer valuations and financing conditions.
The upcoming third-quarter results from major U.S. banks are particularly relevant because investors are examining dealmaking prospects alongside trading revenue and lending growth. Reuters reported that expectations differed among major banks, illustrating why the results need to be assessed institution by institution rather than treated as a single industry-wide signal.
A strong investment banking quarter would not, by itself, prove that the economy is entering a new expansion. Trading revenue can rise because markets are volatile, and a handful of large transactions can materially affect quarterly results. More informative evidence would include a sustained pipeline of mergers, improving capital-market issuance and management confidence that clients are preparing to complete transactions.
For business owners, these trends matter because they influence acquisition opportunities, the availability of financing and the valuations at which companies can raise capital or sell their businesses. What to watch: Mergers and acquisitions, corporate bond issuance, equity offerings, advisory fees and the outlook for future transactions.
Investment Banking in the United States
Investment banking is a financial business that helps companies, governments and large institutions raise capital, buy or sell businesses, issue securities and execute major financial transactions.
Unlike ordinary retail banking, which focuses on consumer deposits, mortgages and everyday banking services, investment banking focuses on large-scale corporate finance and capital markets.
Raising capital. Investment banks help companies raise money by issuing stocks or bonds. Example: A U.S. manufacturing company raises $500 million through a bond offering to build a new factory.
Mergers and acquisitions (M&A). Investment bankers advise companies buying, selling or merging businesses. They help assess valuations, negotiate transactions and structure financing. Example: A large American building-materials company acquires a regional competitor to expand its market share.
Equity and debt capital markets. Investment banks help companies issue shares, corporate bonds and other securities to institutional investors. Example: A growing company lists its shares on the New York Stock Exchange through an initial public offering (IPO).
Financial restructuring. When a company faces excessive debt or financial distress, investment bankers can advise on refinancing, asset sales, debt restructuring or bankruptcy-related transactions. Example: A commercial property owner negotiates with lenders to restructure debt after rental income declines.
The major investment banks in America - The U.S. market includes large universal banks with investment banking divisions and specialist investment banks.
JPMorgan Chase. A major global bank providing investment banking, corporate lending, capital-markets services and transaction advice.
Goldman Sachs. Known for investment banking, mergers and acquisitions advice, securities trading and institutional financial services.
Morgan Stanley. Provides investment banking and institutional securities services alongside wealth and investment management.
Bank of America. Its investment banking business supports corporate clients with financing, underwriting and advisory services.
Citigroup. Provides corporate and investment banking services, including financing and capital-markets access for multinational businesses.
Evercore. An independent investment banking advisory firm particularly associated with M&A and strategic financial advice.
Investment banking makes money
Investment banks earn revenue through several channels.
Advisory fees – Fees for advising on acquisitions, mergers and restructuring
Underwriting fees – Compensation for arranging stock or bond offerings
Trading revenue – Income from market-making and permitted trading activities
Financing – Revenue from providing certain loans and other financing to institutional clients
Asset and wealth management – Separate businesses at firms that offer these services
For example, if an investment bank advises on a $2 billion acquisition and negotiates a fee equal to 1% of the transaction value, the fee would be $20 million. This is an illustration, not a standard market fee; actual fees vary substantially by transaction.
Why investment banking matters to the U.S. economy
Investment banking can help reveal whether American companies are preparing to expand, consolidate or preserve capital.
Rising M&A activity. May indicate that companies see acquisition opportunities, have access to financing or are confident enough to pursue strategic expansion.
More bond and equity issuance. Can indicate that companies are financing new projects, refinancing debt or taking advantage of favorable capital-market conditions.
More restructuring activity. May signal financial pressure, excessive leverage or a need to reorganize businesses and assets.
These indicators need context. A surge in bond issuance, for instance, may reflect companies refinancing existing debt rather than investing in new production. Similarly, high trading revenue can result from market volatility rather than economic strength.
The difference between investment banking and private equity
These businesses often work together but have different roles. Investment banking: Advises on transactions and arranges financing for clients. Private equity: Raises investment capital to acquire stakes in companies, typically seeking to improve their value and eventually sell or otherwise realize the investment. Asset management: Invests money on behalf of clients through portfolios, funds and other investment products. Venture capital: Invests primarily in early-stage or high-growth companies. For example, a private equity fund might decide to acquire an American manufacturing company. An investment bank could advise on the acquisition, help arrange financing or identify potential buyers when the fund eventually exits.
Investment banking is particularly relevant when analyzing: Corporate acquisitions and industry consolidation. Access to debt and equity financing. Commercial real estate transactions. Corporate refinancing and financial distress. The flow of institutional capital into new industries. Investor confidence and expectations for economic growth.
Banks can help identify economic weakness, but the signals are rarely definitive on their own. A decline in loan demand may reflect caution, but it may also mean that companies have sufficient cash to finance their plans without borrowing. Higher loan-loss provisions may signal deteriorating credit quality, or they may reflect a prudent response to uncertainty.
The more concerning pattern would involve several indicators weakening together. Businesses might reduce borrowing while banks tighten credit standards. Consumer delinquencies could rise as spending slows. Commercial property borrowers might struggle to refinance, while corporate clients postpone acquisitions and investment projects.
Such a combination would suggest that financial conditions are beginning to reinforce economic weakness: companies invest less, employment and household income come under pressure, and lenders become more cautious.
The opposite pattern would offer a more encouraging outlook. Sustainable business loan growth, stable repayment performance, improving transaction activity and healthier borrower cash flows would suggest that the economy can continue expanding without a substantial deterioration in credit quality.
Investors should also distinguish between temporary volatility and a persistent change in direction. One weak quarter does not establish a recession, just as one strong earnings report does not guarantee an economic recovery. The objective is to identify whether multiple signals are moving consistently in the same direction.
The third-quarter earnings season offers an opportunity to compare what banks report with what their customers are actually doing. Five indicators deserve particular attention:
First, lending growth. Are businesses borrowing to finance productive investment, and is credit demand broadening beyond large corporations?
Second, credit quality. Are consumers and companies repaying their loans on schedule, or are delinquencies and charge-offs beginning to rise?
Third, funding costs. Can banks maintain healthy margins without paying substantially more to attract deposits?
Fourth, commercial real estate. Are property borrowers refinancing successfully, and are banks seeing meaningful differences between stronger and weaker property markets?
Fifth, corporate transactions. Are mergers, acquisitions and capital-market offerings recovering on a sustainable basis, or are companies remaining on the sidelines?
Taken together, these measures provide a more useful framework than headline bank profits alone. Investors should also compare bank commentary with employment, inflation, consumer spending and Federal Reserve data to avoid drawing conclusions from a single source.
For business leaders, the implications are practical. Companies considering expansion should assess the durability of customer demand, their access to working capital and their ability to withstand higher financing costs. Businesses dependent on consumer spending should monitor repayment trends and purchasing behavior. Property investors should stress-test refinancing assumptions rather than rely exclusively on projected valuations. The goal is not to predict every turn in the economy. It is to recognize changing conditions early enough to make better decisions.
The Banks Are Offering a Window Into America's Next Phase
America's banks are more than financial intermediaries. They are connected to the decisions that drive economic growth: whether companies invest, whether households spend, whether property owners can refinance and whether investors are willing to fund new ventures.
As third-quarter earnings arrive, the most important information may not be the headline profit figures. It may be the details buried in lending trends, credit quality, deposit costs and management commentary.
If business borrowing expands, consumer credit remains sound and corporate transactions strengthen, the evidence would support a more constructive outlook for the American economy.
If lending weakens, repayment problems spread and banks become increasingly defensive, the outlook would be more cautious.
Neither scenario should be assumed in advance. The purpose of examining bank results is to understand which direction the evidence is beginning to point. The next business cycle will not be determined by banks alone. But the choices banks make—and the behavior of the customers they finance—may provide some of the clearest early clues about what comes next.